Statistics
Private Jet Usage Statistics: Who’s Flying Private and How Often
Once perceived as an indulgence, private aviation has evolved into a legitimate strategic tool for businesses and high-net-worth individuals.
 Israel SlodowitzFounder & CEOUpdated October 5, 2026 · Published March 20, 2026 · 5 min read
Once perceived as an indulgence, private aviation has evolved into a legitimate strategic tool for businesses and high-net-worth individuals. Time, accessibility, and comfort all carry legitimate monetary value. Understanding who actually flies private jets, and how frequently they use them, provides insight into a market with far more nuance than meets the eye.
Key Numbers at a Glance
| 1.3M Departures N. America, H1 2025 | +33% vs. Pre-COVID Above 2019 levels | 3.5M+ Global Flights Business jets, 2025 | 91% Operator Confidence Flying same or more in 2026 |
| 45% Owner-Operated Of all business jet activity | +75% Fractional Growth Since 2019 | $190M Median Net Worth Full jet owners | 55% Large Businesses Using private aviation |
45% of Private Jet Use Is Owner-Operated
In North America over the first half of 2025, there were 1.3 million business-related jet departures. Breaking that down by access model reveals a market that’s shifting, with fractional ownership growing fastest of all.
| N. America Business Jet Departures, H1 2025 Owner-Operated ~600,000 · 45% Charter ~420,000 · 32% +4.2% YoY Fractional Ownership ~300,000 · 23% +10.3% YoY |
Fractional ownership is growing at 10.3% YoY, the fastest of any segment. Source: WINGX / ARGUS TRAQPak, H1 2025.
The Financial Profile of Jet Owners
Private jet ownership, and even private jet use, is still concentrated among a narrow financial tier. The numbers below reflect who is actually in the market today.
| Segment | Median Net Worth | Notes |
|---|---|---|
| Full jet owners | $190 million | Median for individuals with complete aircraft ownership |
| Fractional owners | $140 million | Median for individuals using fractional programs |
| Mid/super-midsize owners | $120 million | Average net worth for this cabin category |
| Regular charter users | ~$20 million | Typically paired with ~$2M annual income |
| Minimum for full ownership | $30 million | Recommended minimum net worth |
| Minimum for luxury jets | $70 million | Recommended for larger, high-end aircraft |
| Only 10% of people in the ultra-high-net-worth category actually own private jets, making it a small minority of a minority. The barrier is not just financial; it’s operational complexity, commitment, and capital lock-up. |
The 10% Rules for Safe Ownership
| ✈️ Purchase Price Rule Aircraft purchase price should not exceed 10% of net worth. On a $10 million jet, that implies a minimum $100 million net worth. | 💰 Operating Cost Rule Annual operating costs should not exceed 10% of annual salary. A $10M jet flying 200 hours costs approximately $1M/year to operate. |
Who Is Flying Private?
The demographic profile of private aviation users has shifted meaningfully since the pandemic, and the change is structural, not temporary.
| The Traditional Profile → North American male, age 50 → Banking, finance, or real estate → Full or fractional ownership → Also: mining, agriculture, energy | The Emerging Profile ↑ Average fractional owner age down 10 years since COVID ↑ 81% of affluent 18–35 year-olds are interested in private aviation ↑ High-income millennials prioritizing flexibility over ownership ↑ Remote work driving demand for on-demand air travel |
Corporate and Business Adoption
Corporate and business adoption is one of the most common drivers of private aviation demand. About 55% of large businesses use private aviation, through full ownership, fractional ownership, or charter arrangements.
| Industries Driving Private Jet Adoption | --- | --- |
Light Jet Market Dominance & Aircraft Preferences
Despite the media attention given to ultra-long-range jets, the private aviation market by volume is dominated by smaller aircraft built for efficiency and regional range.
| 48.1% Market Value Large-cabin jets’ share of global business jet market value | 72 Phenom 300 Units Of 155 Embraer deliveries in 2025, best-selling light jet | 100 Cirrus SF50 Units Deliveries in 2025, 2nd consecutive year at 100+ |
| Aircraft Category | Passengers | Range | Speed | New Purchase Price |
|---|---|---|---|---|
| Very Light Jet | 2–5 | Up to ~1,200 nm | ~300–400 kts | ~$3.3M new; $1.5–$2.5M used |
| Light Jet | 4–8 | Up to ~2,000 nm | ~400–500 kts | $4M–$10M |
| Midsize Jet | 6–9 | 2,000–3,500 nm | ~450–500 kts | $10M–$20M |
| Super-Midsize | 8–10 | 3,500–4,500 nm | ~480–510 kts | $20M–$35M |
| Large Cabin | 10–14 | 4,000–6,000 nm | ~480–525 kts | $35M–$65M |
| Ultra-Long-Range | Up to 16 | 6,000–7,700+ nm | ~Mach 0.85–0.925 | $65M–$80M+ |
Top corporate aircraft: Gulfstream G550 (7,500 nm range, Mach 0.925), Bombardier Global Express, Dassault Falcon 7X, Challenger 350, Citation X, Gulfstream G650. Ultra-long-range jets represent 5–10% of units but capture outsized media attention.
Why Private Aviation Demand Continues to Surge
Global business jet activity in 2025 reached more than 3.5 million flights, representing year-over-year growth of just over 6%. Private jet flight activity is now 33% higher than pre-COVID 2019 levels, and the data suggests this isn’t a temporary spike.
| → Business jet departures in H1 2023 were already 13.1% higher than 2019, the growth persisted well after the pandemic → Charter demand has stabilized above 2019 levels, structural demand, not a temporary surge → Fractional fleets have grown 65% since 2019, reaching approximately 1,300 aircraft in service → 89% of operators prioritize performance as a top purchase criterion (up from 82% the prior year), serious long-term investment → 20% of operators have aircraft on firm order, up from 17% the prior year, with charter operators at 28% → Honeywell forecasts 8,500 new business jets worth $283 billion delivered over the next decade, the highest projection in the report’s 34-year history |
Operator Confidence for 2026
| 91% Flying Same or More Total operators expecting continued or increased activity in 2026 | 28% Flying More Operators actively planning to increase flight activity | 64% Flying the Same Operators maintaining current levels, stable demand floor |
A Positive Trajectory That Looks to Last
The fact that private travel rates have increased so dramatically from pre-pandemic norms is a solid indication that the growth trajectory is only likely to continue. Private travel is not just an indulgence for the millions of people who use it every day, it’s a way to unlock speed and convenience that commercial aviation simply cannot match.
It’s true that prohibitively high costs, coupled with considerable depreciation, new planes can lose up to 15% of their value in the first year, remain limiting growth factors. Even so, interest within corporations and high-income families continues to climb, bolstered by more flexible and financially intelligent access models: jet cards, fractional programs, and the investment-based structure that Craft uses.
Where CRAFT Fits
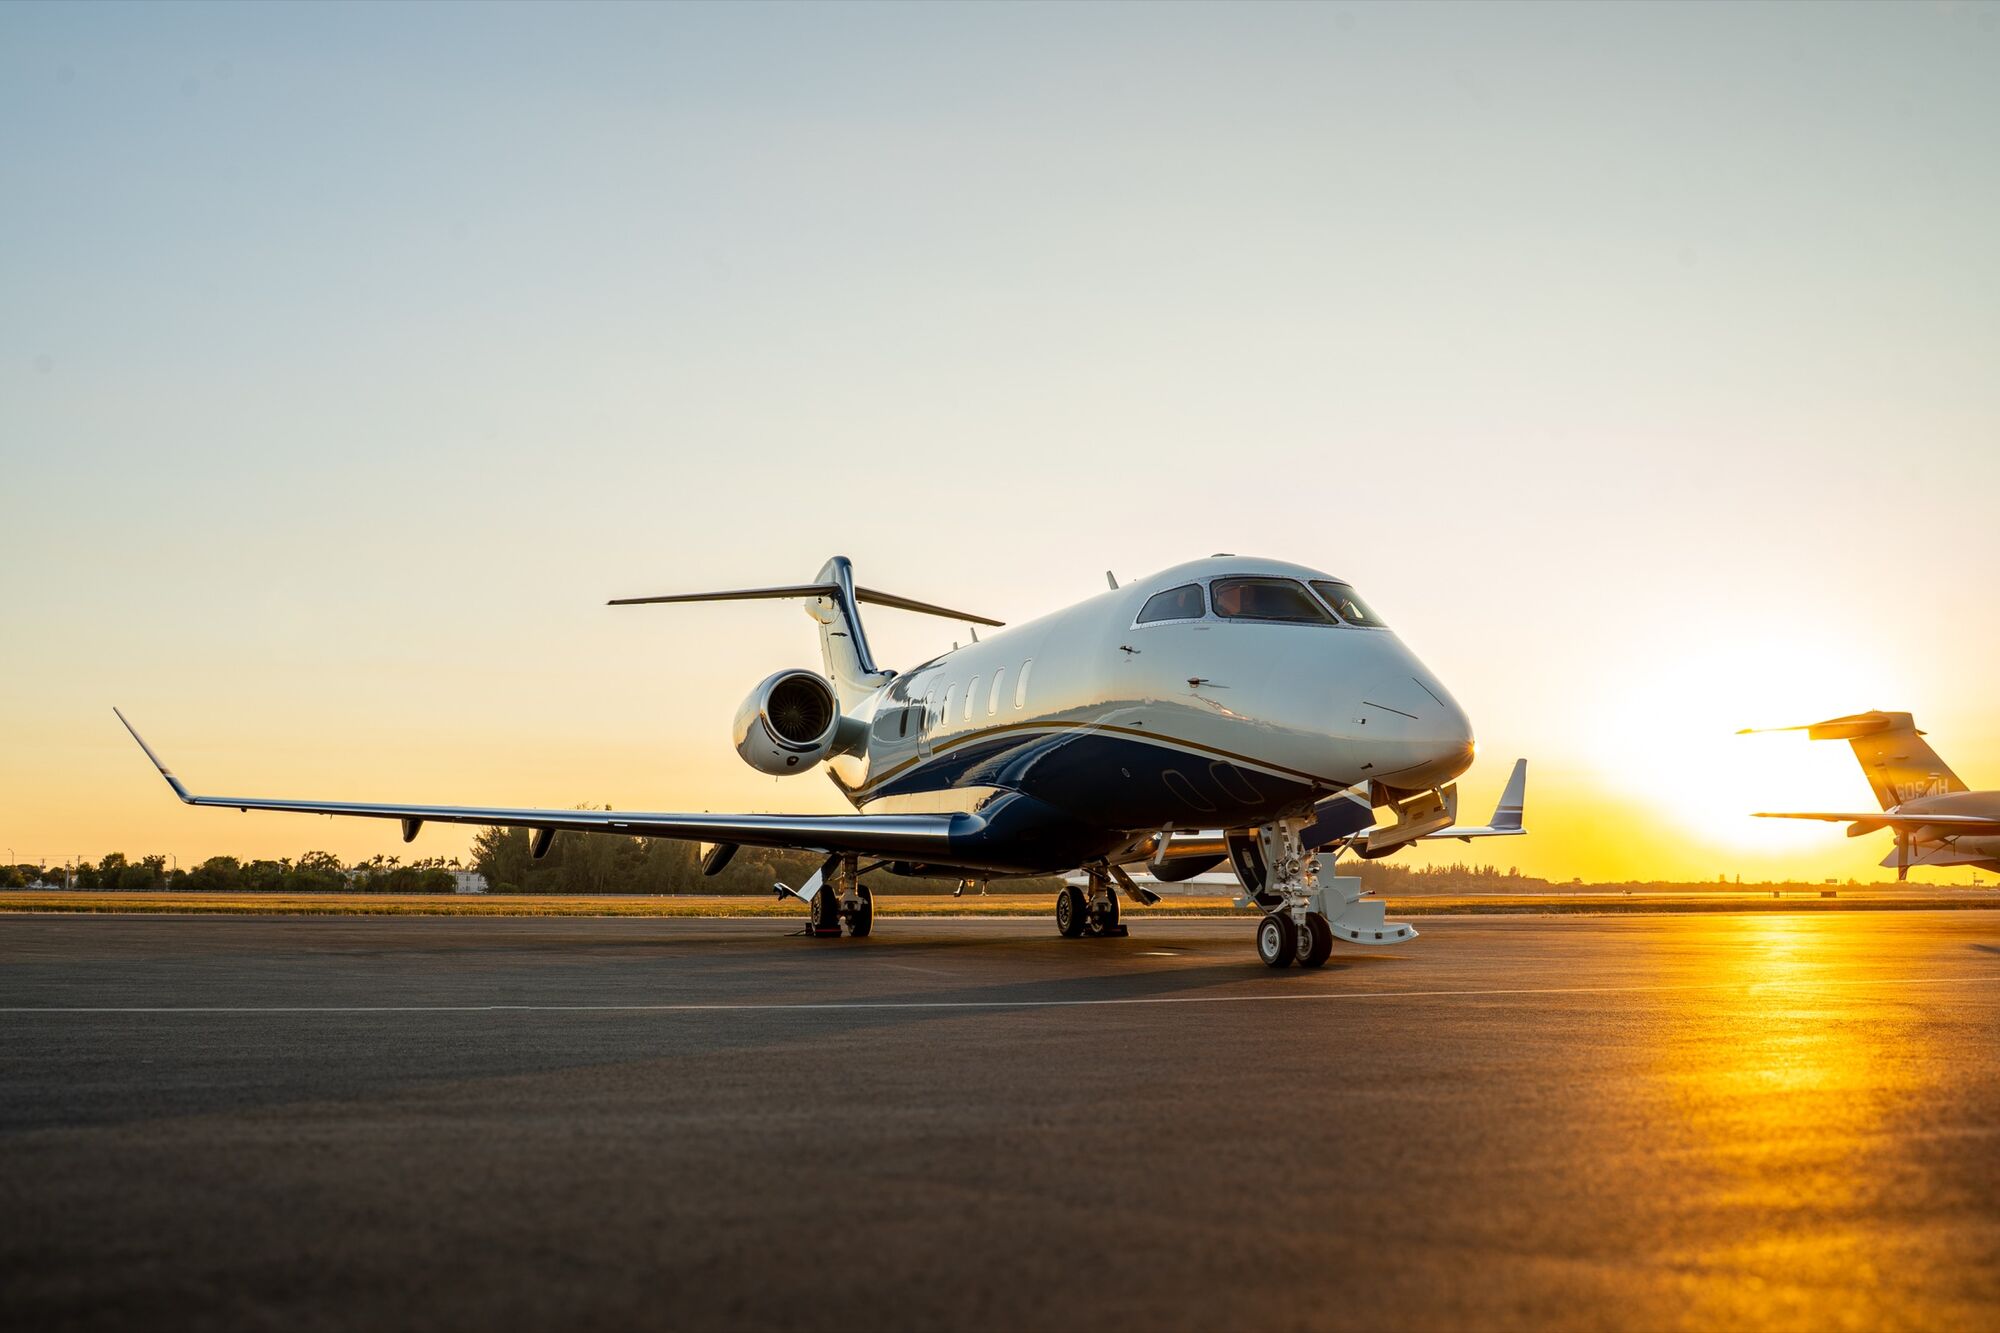
CRAFT is the Part 135 operator of five Challenger 300 and 350 jets. You can charter one trip at a time, or buy hours on the Fleet Jet Card at published hourly rates, fuel and FET included, without buying a share of an aircraft. What a trip costs is on private jet cost by the hour and the city pages, and how card programs compare, route by route, on the jet card providers page.
Related
Related guides
- Empty Leg Flight Statistics: Availability, Savings & Booking Trends
- First Class vs. Private Jet: Cost and Time Comparison Statistics
- Private Jet Operating Costs, Every Model Ranked
- Fractional Jet Ownership vs. Charter: Cost Comparison Statistics
- Private Aviation Depreciation Rates: What Your Aircraft Will Be Worth
Aircraft in this guide
Read next
How much is a private jet?
How much is a private jet? New prices from $3.5M (Cirrus Vision Jet) to $85M (Global 8000), used prices by build year and yearly running costs for 90 models.
October 5, 2026 · 3 min read
Private Jet Ownership Statistics: Costs, Growth & Market Trends in 2026
Private aviation is on the move. In 2026, the global fleet stands at 24,270 aircraft, the market is valued at more than $26 billion, and flight activity has…
October 5, 2026 · 5 min read
Private Jet Passenger Demographics: Income, Age & Usage Patterns
What was once the exclusive privilege of the top 1% of the 1% has become slightly more democratized since the pandemic. Slightly is the important word.
October 5, 2026 · 4 min read
Charter Sales
Tell us the trip. We'll tell you the number.
Route, dates, rough timing, how many people. That is enough to start, and you get a firm price for that specific trip rather than a range.
Text us and you'll get a reply within 60 seconds, any hour.